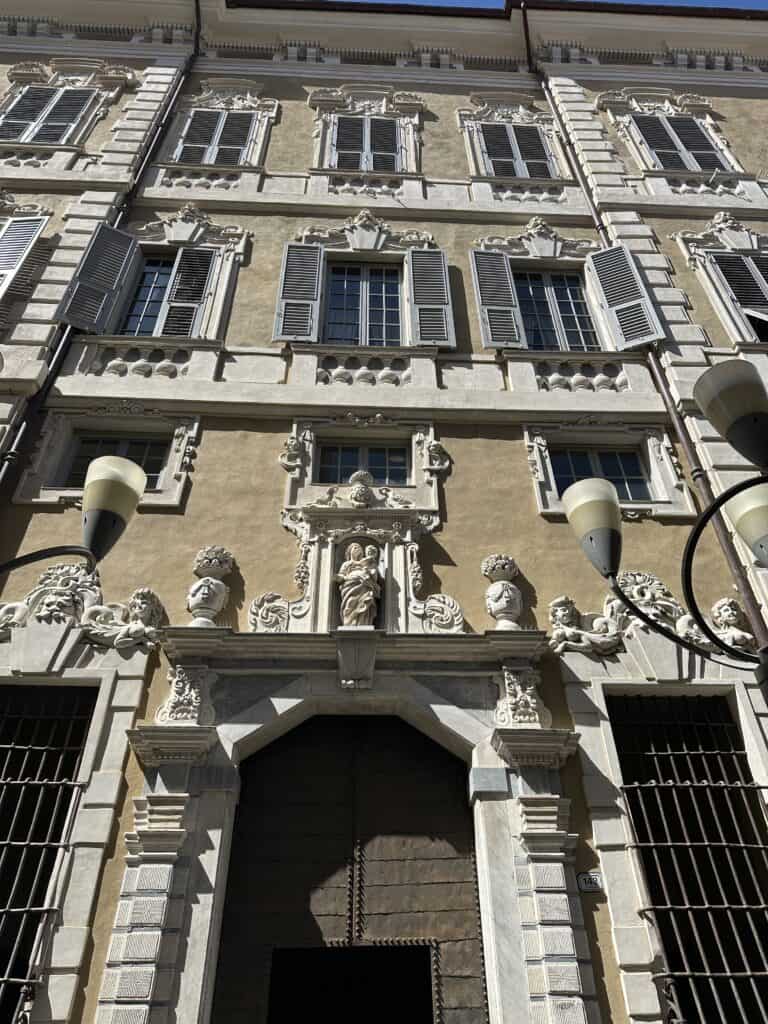
Building in Nice

Living in France as a Retiree: Part 3: Taxes and Succession

Don’t miss Part 1 and Part 2 of this series on Living in France as a Retiree

France has rather rigid laws, especially when it comes to taxation and succession. They are also quite unclear. Disclaimer: I am not an attorney, nor an accountant. However, I can inform any prospective retirees on issues to look out for. I used some of my own experience, but also that of other immigrants from the US to France with different financial and family situations.

Note of caution: French attorneys and tax accountants who deal with Americans tend to ask for a lot of money, and their advice is not always crystal clear. I don’t want to make a sweeping assumption, but this has been our experience.

Another note of caution: Laws change.

No Double Taxation

Who is a French tax resident? The French government uses several factors to determine whether or not you are a resident for tax purposes. A rough rule of thumb is that if you intend to spend more than 6 months of the year in France, you will probably be considered resident for tax purposes.

The good news is that there is a treaty between the US and France, and retirement income, at the very least, is not double-taxed.

Trusts

Many Americans have trusts. France does not recognize US revocable trusts as “transparent” for tax purposes, so every time you change or take a distribution of funds held in a trust, you will have to declare it to the tax authorities within 30 days. The penalties for not doing so are steep.

The current default position is that distributions are automatically treated as income and hence taxable. The onus is on you to prove that distributions are not income and thus not taxable, which means you will need a full accounting trail of the funds. If you have a revocable trust, you should consider removing any financial assets from the trust prior to moving to France.

Joint Ownership of Property

If you are buying property jointly (e.g., you and your spouse or partner), there are three ownership options:

1. En Indivision (Standard Joint Ownership)

This is the default and most common method. Each person owns a specific share (e.g., 50/50 or 60/40) based on their financial contribution.

  • Pros: Simple and flexible; reflects actual financial input.
  • Cons: If one (legal) partner dies, their share is subject to French inheritance laws. This means children (including those from previous relationships) automatically inherit a portion of that share, potentially making the surviving partner a co-owner with their children or stepchildren.
  • Best for couples with no children, or those who are comfortable with their children becoming immediate co-owners when one of the partners passes.

2. En Tontine (Survivorship Clause)

A specific clause is added to the sale deed stating that the survivor is deemed to have owned the entire property from the start. This needs to happen when the property purchase occurs.

  • Pros: The surviving partner becomes the sole owner automatically, bypassing “forced heirship” for that specific property. The children cannot claim their share until both partners have passed away.
  • Cons: It can be difficult to undo if the couple splits up, as both must agree to cancel it. There may also be higher tax implications if the property value is high and the couple is not married or in a PACS (official civil partnership)
  • Recommended for unmarried couples or those with children from previous marriages who want to ensure the survivor stays in the immediate family

3. SCI (Société Civile Immobilière) (Limited Liability Company)

You set up a French LLC to buy the property. The couple (and their children) then owns shares in the company rather than the real estate itself.

  • Pros: Offers the most flexibility for succession planning. Shares can be transferred more easily than real estate, and they can help non-residents manage French inheritance taxes.
  • Cons: Higher setup costs and ongoing administrative requirements (annual accounts). The shares must also be declared to the IRS every year.
  • Recommended for high-value properties or complex family situations where you want to avoid certain French succession rules.

Comparison of Couple Status & Protections

Status: Married

  • Inheritance Tax: Exempt (0%)
  • Automatic Rights: Strongest; can use a Communauté Universelle contract to protect the survivor

Status: PACS (Civil Union)

  • Inheritance Tax: Exempt (0%)
  • Automatic Rights: No automatic inheritance. You must write a French will, or the partner gets nothing

Status: Cohabiting

  • Inheritance Tax: 60% (yes, you read that correctly!)
  • Automatic Rights: None; the surviving partner is treated as a “stranger” for tax purposes

Inheritance Tax on Worldwide Income

When a French tax resident dies, their entire worldwide assets will be taxed by the French authorities. French inheritance tax rates and allowances depend entirely on the familial relationship between the deceased and the beneficiary.

  • Spouse/Civil partner: Fully exempt from inheritance taxes
  • Children/parents: biological, adopted: €100,000 tax-free allowance; above that threshold, a sliding scale: 5% to 45% (progressive)
  • Siblings: €15,932 tax-free allowance; above that threshold, a sliding scale: 35% to 45%
  • Nephews/Nieces: €7,967 tax-free allowance; above that threshold, 55%
  • Unrelated/Friends: €1,594 tax-free allowance; above that threshold, 60%. This category includes unofficial life partners, as well as stepchildren you may have raised, but are not officially your children

More notes of caution:

  • It is important to verify that adopted children will indeed inherit just like biological children; it isn’t always the case, especially if they were adopted as adults.
  • If you have a joint bank account, the wording in the title can determine what happens upon the death of one account holder. It is best to verify this when you open an account.
  • In France you cannot “disinherit” your children. If a couple jointly owns a property and one partner dies, the children of the deceased partner have automatic ownership rights on a portion of the assets and property of the deceased. This cannot be overridden by a legal contract.

The above is not a comprehensive account of all the details. However, at least this article can help retirees avoid some pitfalls and be prepared.

Photo of a building in Nice

Did you enjoy this article? TAIP is 100% reader-supported through tipping. If you want to leave us a tip of any amount it would be highly appreciated.  These tips help support our efforts to keep TAIP an ad-free environment. Just like at a cafe, the tips are split evenly among the team.
Coming down Mont Boron in Nice

Living in France as a Retiree: Part 2: Health Insurance, Medical Care, and Nursing Homes

Don’t miss Part 1 of this series on Living in France as a Retiree

Health Insurance

When you first apply for your long-stay visa for your first year in France, you are required to prove that you have health insurance. The less expensive way of getting it, for me, was via the visa website; it cost about $500 for the entire year, but it was not comprehensive, i.e., not for preventive healthcare, but rather for emergency situations.

Be aware that basic Medicare covers nothing outside of the United States. Some supplemental plans may cover expenses in other countries after a deductible is met.

After you have been residing in France for three months, you can apply for a numéro de sécurité sociale (social security number, which is not the same as Social Security in the United States). You’ll need proof of residence, a birth certificate, and your passport/visa. Usually the application is mailed to the local CPAM office. CPAM (Caisse Primaire d’Assurance Maladie: national health insurance) will probably request additional information by mail or have you fill in a questionnaire. 

The process can be quite daunting and appear illogical. You may be asked for the same document again and again, and then suddenly discover that you’ve been covered for a year! (You can request reimbursement for expenses incurred in the meantime.)

To apply:

  • Your name must be the same on your birth certificate and your passport. If not, you will need to prove that you are the same person through your consulate, and if there’s no consulate only an embassy.
  • If you live with someone without being married or “PACS‘ed” (officially partnered) you may be considered a concubine. It doesn’t have the same connotations as in English, or at least it’s not limited to those connotations. 
  • The CPAM agents usually answer any questions you may have on the phone, and while they are very polite they have little time to speak at length. Telephone number: 3646 (within France). You can request an English speaking agent when you call.
  • You’ll need a French RIB (Relevé d’Identité Bancaire, or bank identity) in order to be reimbursed.
  • To find your local branch, use the Adresses et Contacts (addresses and contacts) section on the Ameli website.
  • More information on French healthcare in English.

Once you have your French social security number, you must request the carte vitale, the health insurance card, which will then be mailed to you. The card is used by medical providers to enter your information, when you fill a prescription or visit a doctor.

Some areas of France are medical deserts, with few medical facilities. In larger towns, you’ll find many hospitals and medical practices, but wait times for specialists can be long and some don’t accept new patients. In Nice, where I live, it’s hard to find a dermatologist — they are often busy with cosmetic procedures!

There are different tiers of medical practices; for some, you don’t need to pay anything over the basic reimbursement offered by health insurance; for others, you’ll pay more. For tier 1 medical practices, you will often pay nothing out of pocket; the national health insurance will handle it.

You can also buy supplemental insurance, through a mutuelle, in a dizzying array of levels. A basic mutuelle subscription might cost €40 a month, and help pay for hospital stays, which can be very expensive. Higher premiums will help pay for hearing aids, glasses, higher-tier medical practice fees… the second year, I used a broker to help me choose.

Nursing Homes and Assistance for the Elderly

In the US, nursing homes often cost much more than many of us can afford, especially in larger cities on the coasts. In France, they are not inexpensive, but appear to be more affordable. There are a variety of systems.

There are senior living facilities for seniors who are well enough not to need assistance, mainly for people who would like to have a community, and in-house facilities.

EHPADs (Établissements d’Hébergement pour Personnes Âgées Dépendantes) are like our medicalized nursing homes. They are meant for people over 60 who need daily assistance. As far as I know, in 2025 they cost about €4,000 a month, but it varies. If you don’t have enough income, you may be able to stay at a lower cost, but when you pass, the difference will be taken out of your estate.

  • Public (government-run) homes cost less than privately-owned homes (nonprofit or for profit).
  • For more information (in French)
  • For a list of locations separated by area: Assistance Retraite (in French)

There are also agencies offering in-house care for a fee. I’m not sure, but if your income is below a certain level, and you are disabled or recovering from a hospital stay, you may be eligible for help paying for a nurse or a cleaning person.

In general, France is a good country to age in, once you have surmounted the bureaucratic hurdles! In my personal view, single-payer insurance is much better than the US system of many disparate for-profit insurance companies, especially as so many get left behind.

Some additional informational websites:

Photo of Mont Boron in Nice

Did you enjoy this article? TAIP is 100% reader-supported through tipping. If you want to leave us a tip of any amount it would be highly appreciated.  These tips help support our efforts to keep TAIP an ad-free environment. Just like at a cafe, the tips are split evenly among the team.
View of Nice

Living in France as a Retiree: Part 1: Participating in Daily Life in France

In two previous TAIP posts (here and here), I explained all the steps needed to start a life in France as a retiree.

In the next three posts, I will explain what you need to take into consideration… very carefully. There are issues that may change your mind, much as you’d like to move to France. 

Public Transportation and Driving

In many parts of France, even in smaller towns, there will be some type of public transportation, even if it’s just a small bus. There are, however, areas such as small villages where buses may be scarce or even nonexistent, and in such cases you will need a car.

I live in Nice, in the city (albeit not downtown), and transportation is very good, especially the closer you are to the coastal area. As a senior citizen, you can get half off the monthly or yearly card. If you use buses and trams every day, transportation becomes very cheap. In a city like Nice, you can also walk to many places (good for your health!). Otherwise, one ride costs 1,70 €  — still not bank-breaking.

Paris and the surrounding areas have a fantastic transportation network: the famous métro, the very fast RER, and many SNCF trains further out to Fontainebleau or Beauvais (where there is a small airport mostly used by RyanAir).

If you need to drive (or just want to drive) and your US driver’s license is not from a state that has an agreement with France, after a year of residence you’ll have to get a French driver’s license. That is an expensive, time-consuming, and difficult proposition, albeit useful to understand French driving laws. If you don’t want to go through that, you need to plan at least a year in advance to obtain an accepted driver’s license, which could entail establishing residence in another state. You’d be surprised which states are not accepted, such as New York and California!

Note: Before you cancel your US car insurance, ask for a letter that shows your claims history (in theory, 14 years’ worth). Otherwise, you’ll be treated as a beginner driver when you buy a car and need to get insurance.

Participating in Demonstrations

Some of us are more political than others. We may wish to march in the street for a variety of reasons, but we have to be prudent when we are not in our own country (even in your own country you have to be careful, but that’s a different story for a different day). I read about an Italian semi-well-known person who was deported from France after she was seen demonstrating, even though she is a citizen of another European Union country; that surprised and worried me.

The good news is that French police are usually (not always) not too aggressive. I have seen demonstrations go by and the police remain close to observe in case of a problem. Otherwise, I have not seen them interfere.

Learning and Speaking French

If you never learned any other language than English in your life, it’s not easy to start learning French as an older adult. But if you are really motivated, you can reach a reasonable level of fluency. It will usually take several years. If you’re in a village with nobody around who speaks English, fluency will be achieved much sooner.

You cannot afford to be ashamed of your pronunciation or incorrect grammar. Practice is key, but so are good classes. It’s hard not to be discouraged when you are convinced you’re saying “une demi-baguette, s’il vous plaît” (a half baguette, please) correctly, and the boulangère (the baker or bakery lady) keeps on saying “Je ne comprends pas” (I don’t understand). Do try practicing “millefeuille” if you love Napoleons! 

There are classes for all kinds of budgets, from a private school in Villefranche to the free version of online language courses. Each person will find their fit according to their budget and learning style; more expensive doesn’t necessarily mean better, although some outlay of cash is necessary, as Duolingo, for one, only goes so far (but it’s a good start). 

Similar to Duolingo, there is Babbel, and several more. I have started using Skool, which has human instructors; this keeps you on your toes. Lawless French is another fantastic tool; Ms. Lawless is a stickler for grammar. Grammar is very important in French, and very complex. The main Lawless French site is free, and there is a paid Kwiziq add-on which is excellent (but don’t believe it when you are told that you have reached C1 level). And of course, there are many private instructors, in person or online. In the US, I used to teach via TakeLessons.

I’ve looked into YouTube videos, and it’s a mixed bag. Learn French with Alexa has proven useful to me as a French teacher. You can thank her by subscribing to her Patreon channel. Videos from some other creators had me seething with rage as they’re just clickbait.

Stay tuned for Parts 2 and 3 on health insurance and medical care as well as taxes and succession laws!

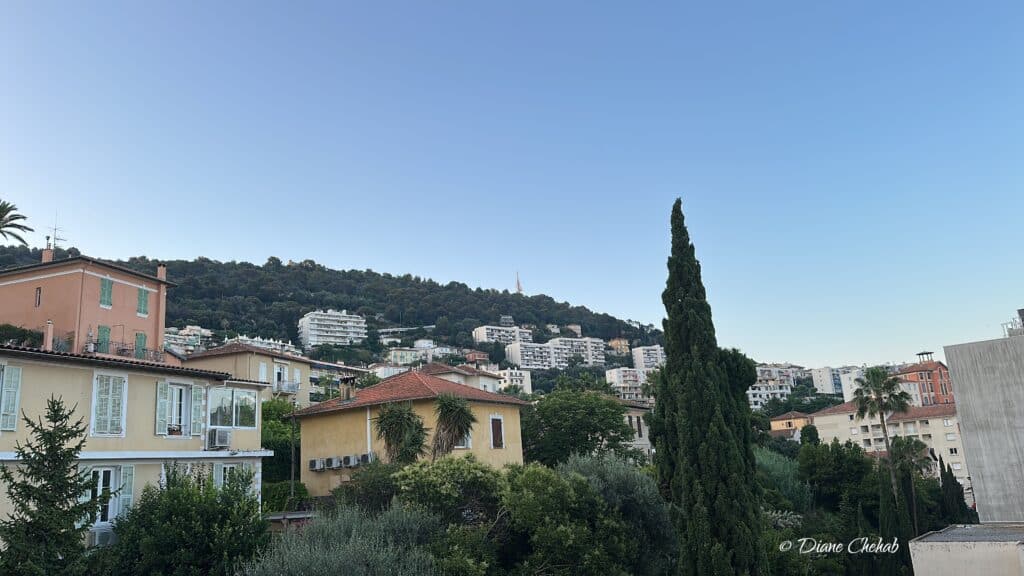
Photo of a view of Nice from a hill.

Did you enjoy this article? TAIP is 100% reader-supported through tipping. If you want to leave us a tip of any amount it would be highly appreciated.  These tips help support our efforts to keep TAIP an ad-free environment. Just like at a cafe, the tips are split evenly among the team.
Building in Nice on Mont Boron: probably Villa Marie Leocadie

Moving to France as a Retiree: The Journey (Part 2)

In Part 1, I described how I applied for a long-stay visa to France as an American retiree, without any EU citizenship or job.

I hadn’t mentioned two items in the visa application process:

  • You will be asked to write and sign a letter promising not to work in France.
  • You need to prove an income of at least the French minimum wage. I provided my pension 1099s, and the Embassy requested a few months of bank account statements to boot.

As you may have already read in the TAIP blog, receiving some work-related income in the US is frowned upon by the French tax authorities. France and the US have a tax agreement and last year I did not have to pay any income tax in France (I had already paid in the US).

Settling Down

With a few months’ respite until the next round of residence applications, it was time to figure out where to live on a long-term basis.

The first few weeks, I was in a series of home exchange apartments in several neighborhoods. I moved on to an Airbnb, then to a studio rented previously from friends of a friend, while looking for a longer-term rental. In Nice, my chosen city, it was just the wrong time: students were moving out of their nine-month rentals, and the apartments were being quickly rented out for the tourist season.

I paid a fee to a rental agency: money down the drain. I went to see a longer-term rental, but there was no kitchen equipment (often the case in some European countries), and I didn’t want to buy an oven and a refrigerator for just a few months, for an apartment I didn’t even like. Finally, the decision was made to buy an apartment, as my partner and I were going to stay in Nice anyway. We found by sheer good luck a wonderful realtor who patiently took us to a variety of places in our chosen neighborhoods (close to public transportation but not too close to tourist and second-home areas) until we found a place that checked many boxes.

Another warning: do your homework about the different ways to own property. In France, a notaire (notary) handles many legal issues that in the US would be handled by an attorney. Ours did not lay out the options for us.

Applying for a Carte de Séjour (Residence Card)

Two months before my visa expired, I went online on the immigration website — the same one where I validated my visa. Now I was in the system, but the site wouldn’t accept my password, and I made the terrible mistake of (in desperation) using my email as a user name. That took me down a rabbit hole, and I found out two months later that I had applied for refugee status! Warning: only log in with the numéro d’étranger!

The login area is on the upper right-hand side. Once you’re “in” you’ll see your history. I was asked for a list of documents, including an e-photo (there are specialized photography studios that will take your photo and provide you with a number.) When you enter the number, your photo pops up. That is a really nice digital feature.

Unfortunately, not everything is as polished. As it turns out, it is almost impossible to ask a question. There is a question area, but it feels like a bot is answering. If you attach the wrong item, you wait about a month before being able to modify it. If you try going to the Préfecture (regional administrative headquarters) without an appointment, you’ll stand in line for 2 hours for nothing, as they instruct you to go online. 15 months went by before I received my residence approval. In the meantime, sometimes I’d get a three-month document to prove that I was allowed to be on French territory. It was nerve-wracking every time I needed to travel outside the EU.

Things may go faster in other regions, where there are fewer foreigners. Southern France apparently is notorious for delays, even for other immigration matters.
There are consultants, but in my humble opinion, I am not convinced they can help things go faster. If you don’t speak/understand French, though, it may be worth it to get precise information. Avoid paying anyone you don’t know large amounts of money.

At the end, the system worked. Next year, I’ll start over for the next carte de séjour! I hope it will be easier, but immigration laws may change and I can’t take anything for granted.

Photo of a building in Nice on Mont Boron

Did you enjoy this article? TAIP is 100% reader-supported through tipping. If you want to leave us a tip of any amount it would be highly appreciated. These tips help support our efforts to keep TAIP an ad-free environment. Just as at a cafe, the tips are split evenly among the team.

View of Mont Boron in Nice

Moving to France as a Retiree: The Journey (Part 1)

At the age of 69, I decided to move to France. 

I had already lived in the Paris area in my youth, first as the child of an expat working for a US company, and then as an architecture student at the Beaux Arts (Fine Arts). Until 2005, I only had French degrees (not on purpose, it just happened due to moving, wars, et al). 

This background is, however, of no interest whatsoever to the French government when I decided to move to France (definitely or indefinitely). I have US citizenship, and that’s it. No European ancestors to call upon, unless a crusader strayed into my forebears, but that would be too long ago, anyway.

I’ll provide the story of my journey (I don’t mean the plane journey, long enough from San Francisco to Nice), from decision to first residence card. A couple of things may have changed in the meantime, but not much, as far as I can tell. I wish I had known all the pitfalls before I started; at least I would have been better prepared.

My first bit of advice is to get on Americans in France blogs, Facebook groups, etc., before you start, rather than afterwards! You can’t believe everything (and you shouldn’t even believe me, without verifying first), but at least you get a lot of information about the pain points.

Before You Pull Up All Your US Roots

  • If you are selling your home, do it before you move to France. Otherwise, you may incur additional capital gains taxes in France.
  • Before you cancel your car insurance, ask for a letter that shows your claims history (in theory, 14 years’ worth). Otherwise, you’ll be treated as a beginner driver.
  • Only some US states have a reciprocity agreement for the driver’s license. 

The Start: the Long-Stay Visa

France is not a country that is especially welcoming to non-EU (European Union) immigrants. There are no golden visas and no special deals. There are many categories of immigrants, and the first action item is to figure out where you fit in. There is no official “retiree” visa: it is a visitor visa. It is only at the expiration of the 1-year visa that you can apply for a residence card.

You’d think the place to apply would be the French embassy or consulate in your area, but no. Visas had been outsourced to a company called VSF Global — now it’s another company, TLSContact. Visas are handled for a variety of countries; the person I interviewed with didn’t even speak French. Before booking an appointment, you fill in an application.

The visa requires health insurance. I got mine via the VFS website, with a company named Mutuaide. Possibly, TLScontact offers links to insurance companies. American insurance companies may be very expensive. **Note from the editor: we recommend Cigna Global for the health insurance needed for your visa application.

You register your account on the TLS site, find the appropriate visa type (VLS-TS), provide the documents they request, and ask for an appointment. Remember, there is no specific retired person visa; you apply as a visitor.

At the appointment, you’ll be asked some questions, get fingerprinted, and hand over your passport, which will be sent to the French Embassy. If the request is accepted, you’ll get it back in about a week or so, with a full page stamp that shows your “numéro d’étranger” (your “foreigner’s number”) that will follow you for the length of your time in France as a foreign resident.

Arrival in France

Once you have arrived in France, you will need to “validate” your visa online. There will be a fee.

Then you receive an email with an appointment for a health check. In 2023, I needed a recent chest scan, but this may not be the case any longer. My scan was a couple of months old, so I had to undergo a new X-ray at the government office on the day of my appointment.

You cannot choose your appointment. If it’s inconvenient, you can cancel it and wait for a new appointment. It took about 6 weeks for me. There is nothing you can do to speed it up. If it’s inconvenient again, well, too bad. I had to cancel a trip.

After the chest scan, you go to another location and fill in a couple of questionnaires. One of my questionnaires was about my mental health. Some questions were tricky: “Do you worry about your weight?” for example. “Have you ever been upset at your coworkers?” (I don’t recall the exact wording.) You undergo an interview with health professionals, and if you pass muster, you are given a receipt that is NOT TO BE LOST (even though nobody asked me for it again).

Health Coverage

After three months in France, you can apply for a Social Security number (this is for healthcare): “ouverture des droits.” 

You’ll need to prove that you live in France (usually via electrical invoices), and provide:

  • Notarized copy of birth certificate (may need to be translated by a certified translator)
  • Copy of passport 
  • Visa or receipt for residence application
  • Proof of residence: for example, a rental agreement, or 3 months of electrical invoices 
  • IBAN (French bank account info)

Make sure the name on your passport is the same as the name on your birth certificate. If you can’t, be prepared to be able to prove who you are!

Most probably, you will receive a questionnaire or a request for more documents. And then you wait, and you wait some more. You may have been approved without even knowing it. Sometimes it’s easy, and sometimes it’s very difficult. You can call them for updates; they have English-speaking agents, but you may not get the correct answer. 

In the meantime, it’s less expensive to get medical care in France than in the US without insurance. 

Taxes

Once you’ve been in France for over 6 months, you will be considered a tax resident. Income taxes are filed around May. The deadline works well for US taxpayers, as we file in April.

There may be a tax office in your town, and it is possible to talk with the counselors; it’s better to go before high tax season starts (I waited for an hour in the pouring rain in April, and at one point someone advised me in the lobby. They were very, very busy).

A Few More Notes

  • US Medicare does not cover overseas expenses
  • Beware requesting a 6-month visa instead of a 1-year visa on the TLS website; you won’t be able to request the carte de séjour (residence card)
  • American Express is not widely accepted in Europe, and they charge fees for overseas charges
  • US credit card companies will not automatically cover your overseas expenses in the unfortunate case of your card being stolen and used before you can block it
  • When you get money at an ATM, it is usually preferable to choose to get the money in euros, rather than have it converted by the bank managing the ATM. Unless the US dollar is in free fall. You never know

This first part covers my experience of getting your foot into France! Stay tuned for Part 2 for the next part of the saga. 

Photo of the view of Mont Boron in Nice.

Did you enjoy this article? TAIP is 100% reader-supported through tipping. If you want to leave us a tip of any amount it would be highly appreciated.  These tips help support our efforts to keep TAIP an ad-free environment. Just like at a cafe, the tips are split evenly among the team.